Your exchange app shows a euro balance. It does not tell you whose name appears on the account behind it.
For an EU crypto customer, that missing detail can matter more than a reassuring "segregated" label. This explanation concerns the Markets in Crypto-Assets Regulation, or MiCA, and its treatment of client fiat funds. It does not assess a particular provider or apply the same rule worldwide.
Start with the provider's legal role and the asset
A crypto-asset service provider, or CASP, is the regulated business in this discussion. A payment service provider, or PSP, can be a different business handling the payment account. One brand in an app is not enough to identify those roles.
MiCA Article 70 distinguishes client crypto-assets from client funds other than e-money tokens. Paragraphs 2 and 3 address ownership safeguards, restrictions on the provider's own use, and placement of those funds.
There is an important exception: paragraph 5 says paragraphs 2 and 3 do not apply to CASPs that are themselves electronic money institutions, payment institutions or credit institutions. Do not apply the placement rule to every business with a crypto interface without identifying its legal status. The exception does not answer which other rules apply.
A token balance needs its own analysis. Our stablecoin explainer covers reserve and redemption mechanisms; it is not interchangeable with the client-fiat arrangement discussed here.
Temporary payment-account holding has a deadline
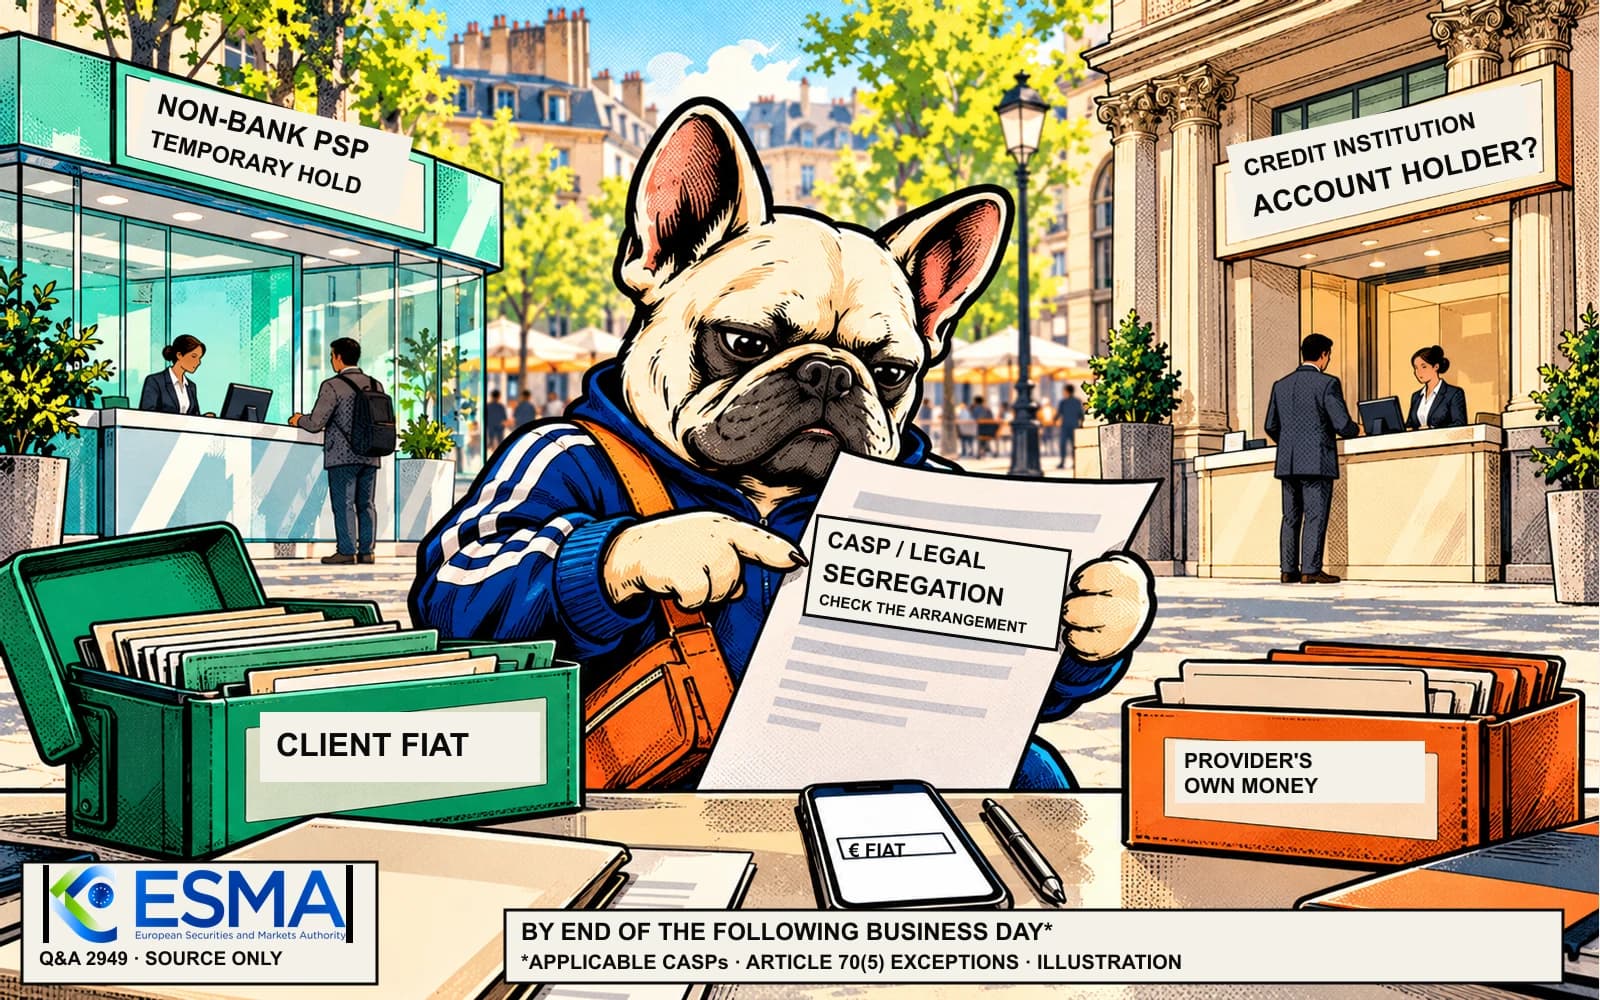
ESMA's Q&A 2949 considers an authorised CASP using a non-bank PSP, such as a payment institution or electronic money institution. It allows temporary holding while the CASP maintains the applicable safeguards.
For the rule under discussion, the placement deadline is the end of the business day following receipt. It is not a blanket 24-hour timer or the customer's withdrawal deadline.
Consider a fictional sequence. Call the receipt day A and the following business day B. Temporary holding on day A is only one part of the arrangement. The relevant placement needs to be completed by the end of B. This example deliberately assigns no weekday, holiday calendar or clock time. It cannot tell you the deadline for an actual payment.
The account holder matters after that deadline
ESMA says the bank or central-bank account must be maintained directly in the CASP's name or under the applicable legal asset-segregation arrangement. A bank account held in the non-bank PSP's name is insufficient for Article 70(3), even if bespoke for the CASP and technically separated. The CASP would still have a claim against that PSP.
| Arrangement being described | What the checked sources establish |
|---|---|
| Temporary holding at a non-bank PSP | Permitted in the Q&A with safeguards and the placement deadline |
| Bank account in that PSP's name, bespoke and technically separated | Does not satisfy Article 70(3) under ESMA's answer |
| Direct CASP account or applicable legal asset-segregation arrangement | The required account-holder distinction; actual compliance still needs the arrangement's facts |
The wording "held at a bank" therefore leaves a question open: who holds the account? A technical label and a legal ownership arrangement are different kinds of evidence.
Safeguarding does not identify your personal protection
Article 70(3) also requires the client-funds account to be separately identifiable from accounts holding the CASP's own money. That separation requirement should not be read as proof that each customer has an individual bank account.
Neither the app's euro symbol nor this placement rule establishes your deposit-guarantee eligibility. You would need the actual account, legal entity, terms and applicable protection scheme. This article makes no positive or negative insurance decision for any customer.
It also cannot infer a withdrawal completion time from the provider's placement deadline. Those questions concern different actions. Check the service's actual terms rather than treating a safeguarding statement as a cash-access promise.
Crypto custody is separate again. Wallet and custody models explain who controls blockchain access; a private key does not identify the legal holder of an offchain bank account.
Questions a useful client-funds explanation should answer
When reading a provider's documents, keep a short record:
- Which legal entity provides the crypto service, and which provides the payment service?
- Is the balance fiat money, an e-money token or another crypto-asset?
- Which safeguarding rules does that entity say apply?
- Who holds the relevant bank account, and how does the arrangement separate client money from the provider's money?
- What do the actual withdrawal terms and any separately identified protection scheme say?
Article 70(4) requires relevant payment services to be provided by an appropriately authorised entity, directly or through a third party, with information about the service and provider. Use that disclosure to identify the parties. This checklist is for understanding documents, not a legal compliance certification or advice to move funds.
Our report on ESMA's non-MiCA stablecoin-services opinion concerns a different question: services involving certain tokens. It does not settle where a customer's fiat balance is held.
Sources and dates
Checked October 18, 2026. ESMA's page dates the question August 28 and its answer October 6, 2026. This is an evergreen explanation of that clarification and existing MiCA provisions, not a new October 18 law or announcement.
- ESMA Q&A 2949: complete question and answer on non-bank PSP accounts.
- MiCA, Regulation (EU) 2023/1114, original act.
- The current consolidated text linked by EUR-Lex, dated January 9, 2024: Article 70 read in full, including paragraph 5.
No provider account, bank arrangement, deposit-insurance claim or withdrawal was tested. Application to an individual case requires its facts and appropriate professional advice.
See something wrong? Brokzi logs material changes. Prepare a correction note.